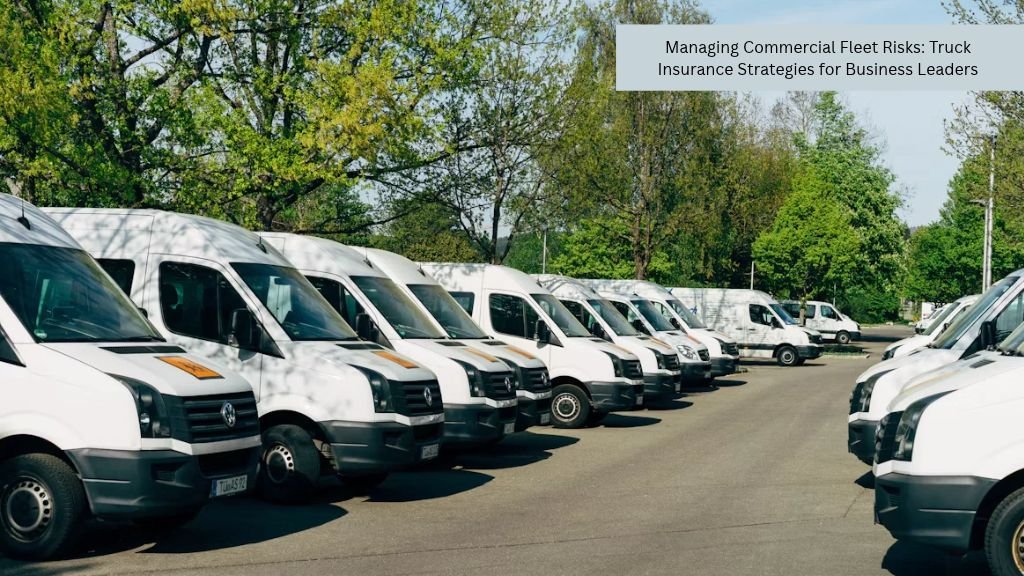


Commercial fleets face a mix of operational, financial, and safety risks every day. A single collision, cargo claim, or extended repair can disrupt schedules and strain cash flow. Business leaders can limit those effects by treating insurance as one part of a wider risk management system that also covers driver standards, vehicle maintenance, and incident reporting.
The strongest strategy connects coverage decisions to real operating data. That gives you a clearer view of where losses begin, which controls are working and how much risk the company can reasonably retain.
Start with a clear picture of fleet risk
Before reviewing policies, document how the fleet operates. Insurers may ask about vehicle types, travel radius, cargo, annual mileage, driver experience and past claims. Your answers affect coverage options and pricing, so general estimates can hide risks or produce unsuitable terms.
Build a fleet profile that records each vehicle’s age, value, use and typical route. Include leased vehicles, temporary replacements and any units used only during busy periods. Next, map the people and processes around them. Who approves drivers? How often do you check records? Who schedules maintenance? What happens after an incident?
A written risk management plan can bring these details into one place and assign responsibility for each control. For example, an operations manager might own vehicle inspections while human resources manages driver files and training records.
Look for concentrations of risk as well. If half of your deliveries run through one congested corridor during the evening rush, that pattern deserves attention. The same applies when one vehicle type produces a disproportionate share of repair costs. A risk register can rank each exposure by likelihood, possible financial impact and the strength of current controls.
Review that register at least quarterly. Fleet conditions change quickly when a company adds routes, hires drivers or takes on different cargo.
Match insurance to actual operations
Commercial truck insurance should reflect what the business does now, not what it did when the policy first began. A fleet that has expanded into new service areas or added higher-value vehicles may have coverage gaps even if every renewal was paid on time.
Start by reviewing liability limits, physical damage coverage, cargo protection, and provisions for hired or non-owned vehicles. Check deductibles alongside limits. A high deductible may reduce premiums, but it can create a serious cash demand if several vehicles are involved in separate incidents during the same month.
Policy language matters too. Ask how the insurer values a damaged vehicle, which drivers are covered, and what reporting deadlines apply. Confirm how temporary replacement vehicles are handled. If a truck is unavailable for three weeks, the cost of renting another unit and losing delivery capacity may exceed the repair bill.
Pennsylvania businesses comparing coverage can speak with American Insuring Group about commercial insurance options suited to their operations. Before meeting with any insurance professional, bring an up-to-date vehicle schedule, driver list, loss history, and forecast of planned fleet changes. That information supports a more useful coverage review.
Set a calendar reminder 60 to 90 days before renewal. This leaves enough time to correct records, discuss loss trends, and compare terms without making rushed decisions days before expiration.
Reduce claims through driver management
Driver behavior has a direct effect on collisions, vehicle wear and insurance costs. A consistent driver management program should begin before a person receives keys and continue throughout employment.
Use written hiring standards that cover experience, driving history and required qualifications. Apply the same process to every candidate in a similar role. Once hired, drivers need practical instruction on company procedures, vehicle inspections, load handling, route expectations and incident reporting.
Distraction deserves direct attention. The National Highway Traffic Safety Administration explains that activities such as reading messages or entering navigation details can pull visual, manual and mental attention away from driving. Company rules should tell drivers when and where they may use mobile devices, including hands-free systems. Dispatchers also need to respect those rules and avoid expecting immediate replies while a vehicle is moving.
Use coaching data carefully. Telematics may identify hard braking, rapid acceleration or speeding patterns, but one event rarely tells the full story. A hard stop could indicate poor following distance or a successful response to a sudden hazard. Review context, speak with the driver, and track repeated patterns before taking corrective action.
Recognition can support the program as well. A driver with a year of safe performance, timely inspections, and complete reports provides a useful model for the rest of the team. Clear feedback tends to work better than rules that only appear after something goes wrong.
Make maintenance records work harder
Preventive maintenance protects more than vehicle reliability. Good records can show that the company followed established procedures before an incident, while incomplete records may make it difficult to demonstrate responsible fleet oversight.
Set service intervals using manufacturer guidance, mileage, engine hours, and operating conditions. Vehicles that spend long periods in stop-and-go traffic may need attention sooner than those traveling steady highway routes. Assign someone to monitor upcoming service and remove overdue vehicles from dispatch until required work is complete.
Daily inspection procedures should be easy to follow and document. Drivers need a clear method for reporting tire concerns, warning lights, fluid leaks, brake issues, and damaged mirrors. A defect report should trigger a defined response, including who reviews it and who decides whether the vehicle can remain in service.
The FMCSA Safety Planner offers guidance that businesses can use to organize safety controls and identify areas that need closer review. Even fleets operating under different requirements can adapt the basic principle: document standards, assign owners, and verify that work was completed.
Digital maintenance systems can help, but a spreadsheet may be enough for a small fleet if it stays accurate. Record the date, mileage, reported issue, repair performed, parts used, and person who approved the vehicle’s return. Review recurring repairs each month. Three similar failures across related vehicles may point to a component problem, harsh operating conditions or a gap in inspections.
Build an incident response process before it is needed
The first hour after a collision or loss can shape the claim. Drivers who are unsure what to do may miss key details, delay reporting, or make statements based on incomplete information.
Put a short response guide in every vehicle and make it available through the company’s mobile system. It should provide emergency instructions, internal contacts, and the insurer’s reporting information. Drivers should know how to document the location, weather, road conditions, visible damage and contact details for involved parties. Photos should be taken only when it is safe and lawful to do so.
Internal reporting should begin promptly, even when damage appears minor. A small scrape can later involve additional repair costs or a third-party claim. Early notice lets the insurance carrier preserve evidence, contact relevant parties, and explain the next steps.
After the immediate response, conduct a structured review. Focus on what happened, which controls failed, and what change may prevent a repeat. Blame-focused meetings often produce defensive answers and little useful information. A review of route timing, dispatch messages, inspection records and vehicle data can reveal contributing factors that weren’t visible at first.
Broader fleet risk management also connects claims control with stable business growth. Track incident frequency, claim severity, repair downtime and preventable event rates. Share a short monthly dashboard with operations, finance and senior leadership so corrective work receives the attention and budget it needs.
Use renewal season as a management checkpoint
An insurance renewal should test the quality of the fleet’s controls. Several weeks before the review, compare current operations with policy details and identify changes in vehicles, routes, drivers and cargo. Then examine the past year’s losses for patterns.
Ask specific questions during the renewal discussion. Did the carrier change any exclusions? Are vehicle values accurate? Do deductibles still fit available cash reserves? Can documented training or telematics data support better terms? Also confirm who must receive notice when the business buys a vehicle, hires a driver, or begins operating in a new area.
Keep a decision record after the meeting. Note why the company selected its limits and deductibles, which alternatives were considered, and what operational improvements were promised. That record helps future leaders understand the reasoning behind the program.
The most useful renewal outcome is a short list of measurable commitments. One might be closing overdue maintenance items within 30 days. Another could be reviewing every hard-braking cluster with drivers before the next quarterly meeting. Those commitments turn the insurance process into a practical test of fleet discipline and give leadership concrete results to examine at the next renewal.